

When Steve Jobs launched the iPhone in 2007, there was no App Store. His plan was for developers to build web apps accessed through Safari. That lasted about a year. Developers demanded native access, and in 2008 Apple launched the App Store — bundling discovery, distribution, trust, and payment into a single controlled layer.
That bundle has generated hundreds of billions of dollars. But it was built for humans who browse, tap, and swipe. AI agents don’t do any of that. And this mismatch is about to reshape the platform economy.
Agents need APIs, not app stores
When you tell an agent “book me a table for two tonight, Italian, $50 per person,” the agent doesn’t need to browse the App Store, download OpenTable, and navigate a GUI. It needs to call an API.
This is already happening. In late 2024, Anthropic released MCP (Model Context Protocol) — an open standard that lets AI agents connect to any external service through a universal interface. Think USB-C for AI integrations: before it, every service needed a custom connector; now there’s one standard plug. OpenAI adopted MCP by March 2025. Google followed. By year-end, MCP was donated to a neutral foundation backed by all the major players.
The connection layer of the agent economy will be open. No one will monopolize it, just as no one monopolized HTTP.
So where does the money go?
If connection is commoditized, you have to unbundle the App Store into three layers and ask where value accrues in each.
Layer 1: Connection (MCP). Solved. Open protocol. No money here — it’s plumbing.
Layer 2: Discovery. This is the real war. When you say “get me to the airport,” how does the agent choose Uber vs. Lyft vs. a local taxi? Today you Google it, check Yelp, ask friends. In the agent era, the agent picks for you — and you may never see the alternatives.
Whoever controls the agent’s recommendation algorithm holds enormous power. Google earns over $200 billion a year selling “the right to be discovered” through search ads. Agent-era discovery could be worth more, because agents don’t just show you options — they complete the transaction. The conversion rate approaches 100%.
Three paths are possible: AI platforms build ranking systems and sell priority placement (highest margin, highest trust risk); user preference data drives autonomous decisions (best for users, hard to monetize); or independent ranking platforms emerge that feed structured data to all agents via MCP. Reality will be a mix — likely varying by industry and stakes.
Layer 3: Payment. Almost entirely greenfield, but potentially the most lucrative. If agents handle daily micro-transactions across dozens of services, someone needs to be the payment aggregator. This is where Apple’s real lesson matters.
Apple’s real lesson: it’s the payment layer
Apple’s biggest revenue stream was never discovery. It was forcing every in-app transaction through its own payment system at a 30% cut.
A user discovers Spotify on the App Store — that’s worth maybe $5 in acquisition cost. But that user pays $12.99/month, Apple takes ~$3.90/month, and over three years Apple earns ~$140 from a single user. Almost entirely from payment, not discovery.
Apple can charge 30% because of lock-in. Your iPhone, iPad, Apple Watch, AirPods, iCloud photos, iMessage history — switching to Android means losing all of it. Users are trapped, so developers have no alternative path to reach them, so Apple sets the toll.
Can AI platforms replicate this?
Probably not to the same degree. The agent era lacks Apple’s lock-in mechanics: no hardware ecosystem that only works together, an open connection protocol (MCP works with every agent), portable data, and fierce model competition. If one platform tries to charge high payment fees, users switch to a competitor whose agent accesses the same services through the same MCP servers.
This suggests the payment layer will be competitive and low-margin rather than monopolistic. Discovery is where I’d watch most closely — it’s the one layer where AI platforms have a natural advantage (they are the agent), where monetization potential is highest, and where competitive dynamics are still genuinely uncertain.
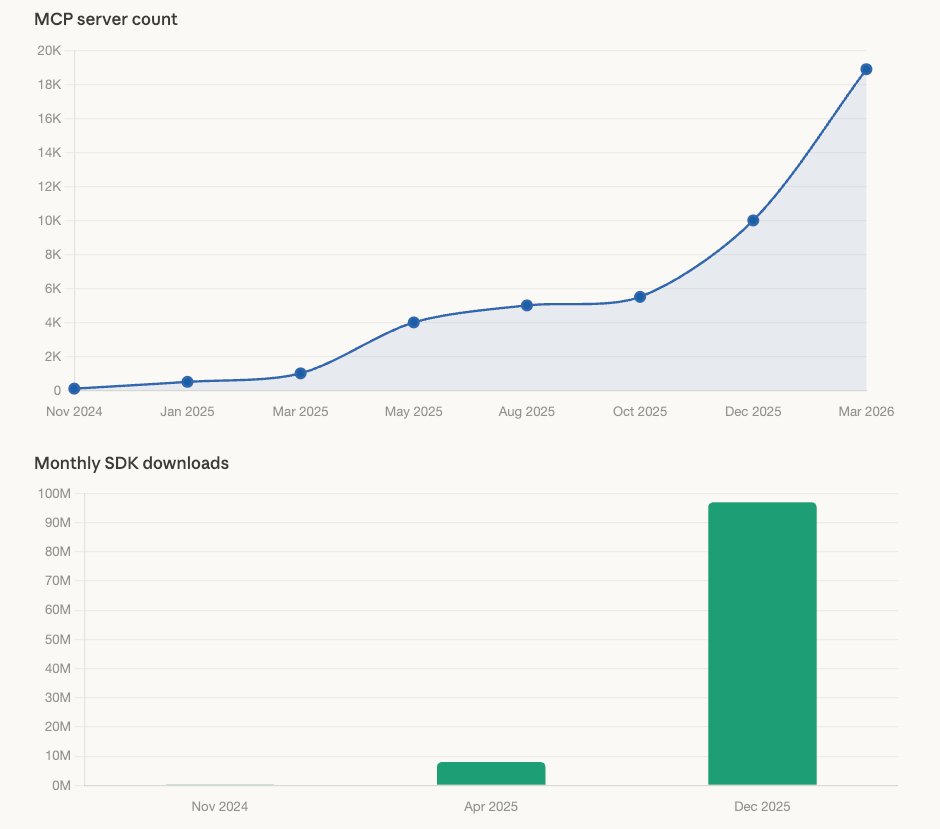
source: https://mcp.so/
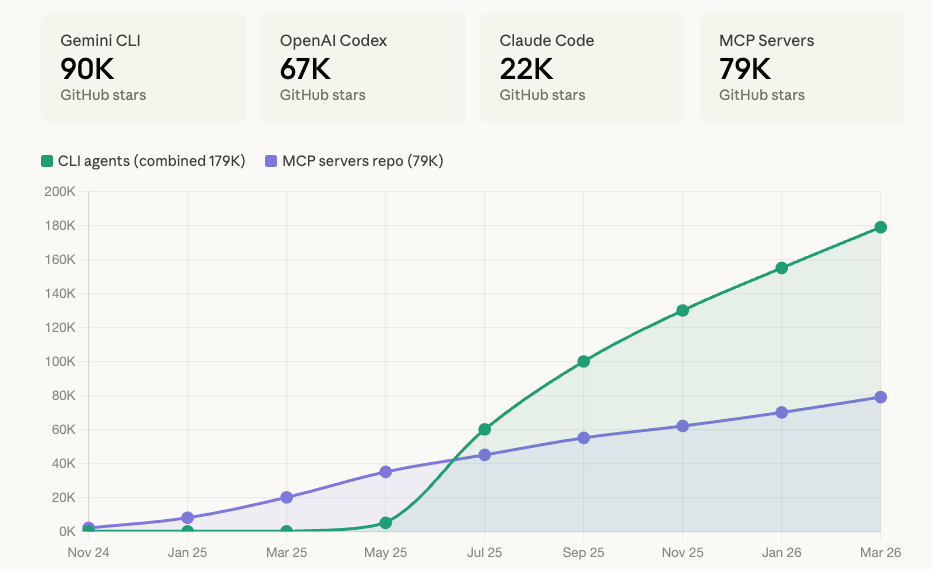
https://github.com/openai/codex/releases
The timeline
More services build MCP adapters. Agent tool ecosystems grow. But agents are still limited — users mostly specify which services to use.
Agents get smart enough to choose services autonomously. “Who decides the ranking” becomes the central commercial and regulatory question — think EU vs. Google Shopping, but sharper.
Agents handle significant daily transaction volume. A unified payment infrastructure becomes necessary. Whoever holds that position holds the minting rights of the agent economy.
The App Store was a product of its era — a centralized answer to the distribution problem of a new computing platform. The agent era needs new answers. They won’t look like an app store.
For Discovery you mention three paths. A fourth that is bidding-like seems equally fitting to this ecosystem dynamics.
Thinking of what happened with human agents - us - we were/are steered by advertisement and biased information more in general. The same might happen for agents.
this changed my thinking in a material way - I appreciate you sharing it